Category: Social

Heritage

  • From Sunlight to Breath: How Climate Shaped the Human Face

    Look at human faces across the world and one feature immediately announces our evolutionary diversity: the nose. Noses differ in height, projection, width and nostril shape from one population to another. These differences are not merely cosmetic. The nose is one of the body’s most sophisticated air-conditioning systems, and its architecture appears to carry an imprint of the environments in which our ancestors lived.

    Every breath begins its journey through the nose. Before air reaches the lungs, the nasal passages warm it, humidify it and filter out particles. The nasal cavity is lined with blood-rich tissue and mucus, while its intricate internal structures, particularly the turbinates, create extensive contact between inhaled air and the warm, moist nasal surfaces. By the time air reaches the deeper respiratory tract, it has already undergone substantial conditioning.

    That makes the nose an obvious candidate for climate adaptation. In cold, dry air, the conditioning job is demanding. A relatively narrow and elongated nasal passage can increase interaction between incoming air and the warm, moist nasal lining. The geometry also influences airflow and turbulence, helping the nose transfer heat and moisture to the air before it reaches the lungs. In warm, humid environments, incoming air requires less warming and humidification, and broader nasal passages may permit airflow with lower resistance.

    Human populations living for thousands of generations in different climates consequently developed different averages in nasal form. The pattern is not absolute—there is enormous variation within every population—but the geographical signal is striking enough to have attracted evolutionary investigation.

    A particularly important study appeared in PLOS Genetics in 2017. Zaidi and colleagues compared variation in nose shape among populations and used QST–FST analysis to ask whether differences were greater than would be expected from genetic drift alone. They found that nares width and alar-base width showed greater differentiation than expected under drift alone. More importantly, nostril width was significantly associated with temperature and absolute humidity: wider nares were more common in warmer, more humid ancestral environments, while narrower nares were associated with cooler, drier environments. The authors concluded that some aspects of nose shape may have been influenced by local adaptation to climate, while cautioning that human evolutionary history is complex and other forces may also have contributed.

    The nose therefore provides an intriguing example of a larger evolutionary principle: environment can leave a measurable imprint on anatomy. Genetics does not deliberately redesign the body when the climate changes. Instead, populations contain inherited variation, and over many generations natural selection can alter the frequency of variants that affect survival and reproduction under particular environmental conditions.

    Skin pigmentation offers an even clearer example. Melanin can be thought of as the body’s biological sunscreen, absorbing and scattering ultraviolet radiation and helping protect tissues from excessive UV exposure. Human pigmentation varies geographically in ways strongly associated with ancestral ultraviolet environments. The nose, by contrast, is less a solar shield than a respiratory climate-control device.

    Together they tell a remarkable story. One part of the human body is tuned, in evolutionary terms, to sunlight; another is partly tuned to the temperature and moisture of the air. Body proportions, facial structure and other traits likewise bear the influence of geography, diet, disease environments and other selective pressures.

    This does not mean that humanity consists of neatly separated biological races. Human populations have always migrated, mixed and exchanged genes, and most human genetic variation exists within populations rather than between rigid racial categories. What we see as racial or ethnic differences are therefore better understood as overlapping patterns of population variation, produced by a complicated mixture of ancestry, migration, genetic drift, natural selection and historical circumstance.

    Evolution has no master plan and no preferred human appearance. It works locally, generation after generation, through the relentless interaction between inherited variation and the environment.

    The result is written on our faces. Dark skin can reflect adaptation to intense ultraviolet radiation. A nose can reflect adaptation to the demands of breathing cold, dry or warm, humid air. Our faces are, in a sense, evolutionary maps—records of where our ancestors lived and the physical challenges they repeatedly encountered.

    The next time we look at a human face, therefore, we are not simply seeing appearance. We are seeing the accumulated history of an extraordinary species learning, generation by generation, how to live with the planet. PT
  • Six Million Years of Bipedal Walking: Sahelanthropus, Orroin, and the Dawn of Humanity

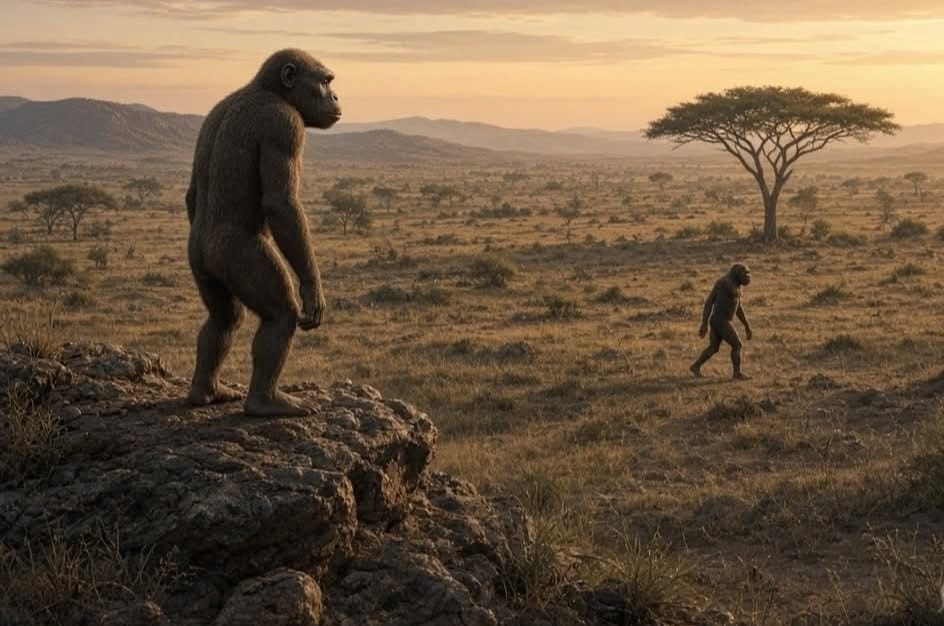
    The earliest chapters of the human story are written in the scattered bones of two small, bipedal creatures who lived in Africa some six to seven million years ago. Sahelanthropus tchadensis and Orrorin tugenensis stand at the threshold of our lineage, the first known species that can reasonably be called human in the broadest scientific sense. They were not modern people. They were not a founding couple. Yet they mark the moment when a group of African apes began to walk upright more often than not, setting in motion the long experiment that would one day produce Homo sapiens.

    Sahelanthropus tchadensis, discovered in the deserts of Chad and nicknamed Toumaï, lived between seven and six million years ago. Its nearly complete skull shows a mosaic of features: a brain the size of a chimpanzee’s, a sloping face, yet unusually small canines and a foramen magnum positioned in a way that suggests the head was balanced atop a more vertical spine. Later finds of a partial femur have been interpreted by some researchers as evidence of habitual bipedalism, though the claim remains contested. What matters is the timing. This creature lived at or near the evolutionary split between the line that led to chimpanzees and the line that led to us. Whether it sits just on our side of that divide or very close to it, Sahelanthropus is the oldest serious candidate for the first human species.

    A little later, around six million years ago, Orrorin tugenensis appears in the Tugen Hills of Kenya. Its name means “original man” in the local language, and its fossils, especially the thigh bones, offer clearer signs of upright walking. The shape and thickness of the femoral neck resemble those of later bipeds more than those of knuckle-walking apes. Like Sahelanthropus, Orrorin retained climbing abilities, moving between trees and open ground in a landscape that was already beginning to fragment. Together these two species form the opening act of the hominin radiation. They lived, reproduced, and died in social groups whose size and structure we can only guess at. But they represent the first known departure from the purely quadrupedal life of the earlier apes.

    From that distant starting point the family tree branched rather than climbed. Over the next several million years more than twenty related species appeared. Some, like the various australopiths, flourished for long periods. Others, such as the robust Paranthropus forms, specialized and then vanished. Members of the genus Homo emerged around 2.8 million years ago. Later still came the Neanderthals, the Denisovans, the island dwarfs of Flores and Luzon, and Homo naledi. Many of these were cousins rather than direct ancestors. Our own species, Homo sapiens, is a late arrival, first appearing in the African fossil record roughly 300,000 years ago. The genetic lineages known as Mitochondrial Eve and Y-chromosomal Adam are younger coalescence points within that species.

    Evolution works through changing populations across deep time. Sahelanthropus and Orrorin were the earliest known members of the broader human family. They were the first leaves on a bush that would grow crowded with relatives, most of whom would eventually disappear. What these two species give us is a sense of scale and continuity. The human story did not begin with the polished tools or the large brains of later forms. It began with small bipeds testing a new way of moving through a changing world. Everything that followed—the expansion of the brain, the mastery of fire, the spread across continents, the eventual solitude of our own species—rests on that ancient shift. In acknowledging Sahelanthropus tchadensis and Orrorin tugenensis as the first human species, we accept both the depth of our origins and the crowded company in which those origins unfolded. We are the last of a once diverse family, and the first of that family were already walking upright millions of years before any of us arrived. OK

  • The Rupee Squeeze: How Imported Inputs and Foreign Capital Outflows Endanger India’s Stability

    India’s macroeconomic narrative often presents a picture of resilient, self-sustaining expansion, yet beneath the surface lies a complex interplay of structural vulnerabilities that span from the agricultural field to the foreign exchange desk. While the nation takes pride in its domestic self-sufficiency across fundamental food staples like wheat and rice, a critical dependency remains unaddressed. India’s true food security is acutely exposed to global supply chains, relying heavily on foreign nations for over half of its edible cooking oil requirements, essential pulse varieties, and the bulk of its agricultural inputs. This reliance means that domestic agricultural stability is fundamentally tied to international trade corridors, maritime security, and foreign currency swings.

    The vulnerability of this framework becomes particularly stark when examining fertilizers. India imports its entire supply of Muriate of Potash and over half of its Di-Ammonium Phosphate, alongside the imported liquefied natural gas required to manufacture domestic urea. When global geopolitical frictions flare or capital flows reverse, the cost of securing these vital nutrients escalates sharply. This structural weakness is exacerbated whenever foreign portfolio investors exit Indian markets, driving down the value of the Rupee. Because these agricultural inputs are priced globally in US Dollars, currency depreciation automatically inflates their landed cost in domestic terms.

    This financial dynamic confronts policymakers with an unavoidable dilemma. The government can either absorb these currency-driven cost increases by expanding the fiscal deficit through higher public subsidies, or it can pass the burden directly onto smallholder farmers. Choosing the latter risks under-application of essential fertilizers, diminished crop yields, and severe retail food inflation. Choosing the former strains sovereign fiscal health, which can paradoxically trigger further foreign capital flight and deepen currency pressures. The agricultural sector thus sits directly at the intersection of international monetary movements and real-economy supply constraints.

    At the same time, recent developments in banking liquidity reveal how global financial flows can alter internal market dynamics in unexpected ways. A massive influx of foreign currency deposits—totaling roughly 127 billion dollars—provided domestic commercial banks with an unprecedented cushion of foreign liability funding. When these dollars were converted into local currency through central bank swap mechanisms, they flooded the domestic banking system with excess Rupee liquidity. This surge in short-term bank funds drove down money market yields and Certificate of Deposit rates, as institutions substituted wholesale market borrowing with foreign currency deposits.

    Yet this internal liquidity abundance exists alongside cautious central bank interventions. To prevent this vast pool of excess Rupee liquidity from distorting short-term interest rates and pushing money market yields far below policy targets, the Reserve Bank of India has had to mop up hundreds of thousands of crores through large-scale Variable Rate Reverse Repo operations. Concurrently, strict guardrails have been imposed on the offshore Non-Deliverable Forward market to prevent speculative short-rupee bets and restrict arbitrage between offshore and onshore foreign exchange rates. These interventions demonstrate that while real-money foreign deposits can temporarily ease domestic bank funding costs, they do not dissolve the underlying exchange rate risks or the broader structural vulnerabilities of an economy reliant on imported real-world commodities.

    Compounding these structural and monetary pressures is a notable shift in real economic momentum. Private survey metrics, including recent Purchasing Managers’ Index releases, point to a gradual cooling in service sector activity—the traditional engine of India’s post-pandemic growth—alongside a broader moderation in manufacturing output. Although the service sector continues to expand and maintain employment creation, cost pressures regarding energy, labor, and digital infrastructure remain sticky, while business confidence has normalized toward historical averages.

    Ultimately, these interconnected dynamics illustrate that India’s economic health cannot be insulated solely through monetary engineering or short-term liquidity management. A surge in bank liquidity may soften wholesale borrowing rates, and central bank auctions may temporarily absorb excess domestic cash, but neither can produce domestic potash or cultivate edible oilseeds. To secure true long-term stability, India must translate its monetary policy buffers into structural real-economy solutions—diversifying agricultural crop patterns, scaling local alternative nutrients, and insulating domestic food supply chains from external currency and geopolitical shocks. NI

  • Economic Tightrope: Geopolitics, Market Flows and India’s “Resilience”

    Global trade networks and domestic financial systems are increasingly intertwined, putting India at the center of complex geopolitical shifts and evolving market dynamics. The United States Treasury recently launched “Operation Economic Outcast,” an aggressive sanctions campaign designed to choke off Iran’s revenue streams across key sectors including digital assets, technology, gold, aviation, and shipping. This aggressive posture explicitly places key trade partners on notice—giving India and other countries a defined timeline to voluntarily sever economic ties with Tehran or risk secondary sanctions and exclusion from dollar clearing networks. The concrete reach of this enforcement policy quickly manifested when the U.S. State Department designated four India-based companies and three Indian nationals for allegedly facilitating over $119 million in Iranian petroleum and petrochemical transactions. Entities such as Sadashiva Overseas Limited, PP Softtech, Prakrutees Infra Impex, and customs broker Portease Partners faced immediate asset freezes, signaling Washington’s intent to target downstream intermediaries, freight forwarders, and trade facilitators to enforce compliance. Despite these intensifying external pressures, India continues to manage its strategic logistics and agricultural dependencies through pragmatism. Although its flagship investment in Iran’s Chabahar Port faces renewed scrutiny under the widened sanctions scope, New Delhi maintains a flexible procurement strategy. For instance, to secure critical crop-sowing seasons against global price shocks, India contracted to import 12 lakh tonnes of urea from China, leveraging coal-based pricing advantages to bypass shipping vulnerabilities in the Middle East.This external volatility forms the backdrop against which Indian domestic financial markets are undergoing a major internal realigning. In the secondary equities market, capital flows reveal a structural shift away from speculative primary market activity. After a frenzy of chasing initial public offerings (IPOs) throughout FY26, retail investors have rotated back to listed equities. Retail net deployment in IPOs dropped sharply from ₹42,608 crore in FY26 to ₹7,134 crore in early FY27, while net buying in secondary market stocks surged to ₹39,053 crore. This pivot reflects valuation realignments following broad mid-2026 corrections, making established secondary equities far more attractive than expensive new listings.Yet, a broader examination of the market’s structural plumbing reveals a deeper dichotomy between participant groups. Foreign Institutional Investors (FIIs) have maintained persistent net-selling pressure, accumulating a massive wall of nearly 1.86 lakh net-short contracts in index futures to hedge their long positions against geopolitical crosswinds. Meanwhile, Domestic Institutional Investors (DIIs) have acted as thel market’s primary shock absorber. DII net purchases eclipsed ₹2.54 lakh crore over the first four months of FY27, counterbalancing massive FII sales exceeding ₹1.80 lakh crore and non-institutional net sales.

    On the real-economy front, domestic industrial activity numbers moderate. India’s Index of Industrial Production (IIP) growth slowed to 6.7% in July 2026 from an upwardly revised 8.8% in June. However, manufacturing expanded by a 7.3%, led by double-digit gains in electrical equipment and automotive production, while capital goods surged 16.1% to demonstrate ongoing private capex momentum. A key internal divergence persists between consumer durables—which grew by 10.5% on urban demand—and consumer non-durables, which contracted by 1.0%, highlighting uneven recovery across rural consumption baskets. Ultimately, as India navigates the economic dragnet of foreign sanctions alongside internal market shifts, its broader economic foundation remains anchored by institutional liquidity, capital investment momentum, and trade policies.

  • Capital Inflows, Stagnant Signals: Decoding India’s Economic Divergence

    The Indian economic narrative is presenting a paradox where internal liquidity is clashing against growing global headwinds and structural friction. On paper, domestic markets ought to be roaring. Domestic institutional investors pumped in a massive ₹34,369.50 crore while foreign institutional investors chipped in another ₹2,514.30 crore during the current month up to yesterday. Yet despite this combined inflow exceeding ₹36,883 crore, the Sensex remains strikingly dormant, trapped in a narrow trading band. Understanding this disconnect requires peering into a broader tapestry of shifting corporate earnings, escalating geopolitical threats, central bank maneuvering, and consumer behavioral splits.

    Much of the equity market’s hesitation stems from the immediate geopolitical arena, where a fresh wave of volatility is threatening energy security and trade logistics. United States President Donald Trump issued a stern warning targeting Tehran, declaring that any country providing Iran with a commercial or financial lifeline will face tremendous economic consequences. This escalation places India in a delicate geopolitical spot. Though India has scaled back direct Iranian oil imports, it maintains crucial non-energy trade and holds key operations at Iran’s Chabahar Port, an essential maritime gateway for Indian commerce into Central Asia and Afghanistan. The threat of secondary sanctions creates compliance paranoia across financial institutions, casting a shadow over cross-border trade settlements and compounding supply concerns as Brent crude hovers near ninety-four dollars a barrel.

    This geopolitical friction feeds directly into domestic monetary strategy. The Reserve Bank of India recently kept its benchmark repo rate unchanged at 5.25 percent, holding a neutral stance to preserve maximum operational flexibility. With headline consumer price inflation recently rebounding above the four percent target due to transient food and energy shocks, the central bank left its future rate path wide open. While raising full-year real gross domestic product growth forecasts to 6.7 percent, policymakers are painfully aware that persistent oil spikes could ignite secondary inflation, forcing them to delay rate cuts or keep monetary conditions tight for longer.

    Compounding this cautious monetary backdrop is the stance of global money managers. In the latest Bank of America Asia Fund Manager Survey, India emerged as the least favoured regional market, with a net thirty-two percent of surveyed managers reporting an underweight allocation. Global capital in Asia has heavily concentrated into pure-play artificial intelligence hardware and semiconductor supply chains across Taiwan, South Korea, and Japan. Lacking direct exposure to these specialized AI hardware supply chains, Indian benchmarks are losing relative foreign portfolio flows to East Asian peers, even as high local valuations invite profit-taking from international funds during currency swings.

    Microeconomic operational reality offers its own set of mixed signals. A clear picture of this internal friction shows up in mobile hardware trends, where smartphone shipments fell eight percent in the first quarter of fiscal year 2027. This slump reflects severe memory component cost inflation and a virtual collapse in the entry-level budget segment, where shrinking margins forced manufacturers to trim low-cost product lines. Across corporate earnings more broadly, India Inc’s latest quarterly performance reveals a widening divide. High-end consumption, banking, capital goods, and auto manufacturers delivered healthy profit beats, whereas oil marketing companies suffered heavily under unabsorbed raw material spikes, and lower-income mass-market demand continued to lag under persistent living costs.

    Yet, despite this heavy list of global constraints, domestic liquidity and balance-sheet buffers are preventing a market breakdown. India’s foreign exchange reserves have surged to comfortable record highs of roughly 717 billion dollars, bolstered by steady dollar inflows raised from Non-Resident External deposit schemes. However, a massive reserve pile manages volatility rather than altering fundamental structural pressure. With the Rupee hovering near the 96 per dollar mark, the central bank uses these dollar reserves to smooth out intraday panic and unwind forward positions rather than defend a specific exchange rate line. High oil import bills and narrowing interest rate spreads mean the Rupee continues to act as an automatic economic shock absorber. Ultimately, domestic liquidity and sovereign reserve buffers have built a floor under Indian equities, but until entry-level consumer demand recovers, that liquidity wall will continue to encounter a heavy ceiling. NI

  • Beyond the Ticker: Why Fiscal Cushions and Foreign Buying Aren’t Calming Street Anxiety

    India’s macroeconomic story is presenting a classic study in contrasts, where balance-sheet metrics and institutional buying clash directly with growing trade vulnerabilities and cautious retail sentiment. On paper, the fundamental pillars of the fiscal engine appear good. The Union Government has already achieved nearly three-quarters of its annual asset-monetisation and disinvestment target. By locking in seventy-four percent of its goal ahead of schedule through strategic stake sales and brownfield infrastructure leases, New Delhi has bought itself substantial fiscal insurance. This capital cushion shields the national balance sheet against volatile global macro shifts, rising domestic subsidy burdens, and unexpected spending mandates. It also reassures international credit agencies that India’s fiscal deficit trajectory remains on target.

    Yet, this internal fiscal discipline stands in stark relief against a widening economic leak along the external frontier. In July 2026, the national merchandise trade deficit expanded to a six-month high of nearly thirty-two billion dollars. While domestic manufacturing and export engines hit historical records—propelled by a staggering seventy percent spike in petroleum exports and nearly sixty percent growth in local electronics production—the national import bill surged even faster. Driven by an eighteen percent rise in crude oil costs and massive inflows of industrial machinery and electronics components, imports topped seventy-six billion dollars for the month. This surge reflects an uncomfortable structural dependence on imported energy and raw materials.

    This widening external gap quickly spilled over into domestic capital markets, exposing a fascinating psychological rift among investors. Over the course of a single week, domestic institutional investors pumped over seventeen thousand crore rupees into Indian equities, backed by an additional four thousand crore rupees from foreign institutional buyers. In total, over twenty-one thousand crore rupees in net institutional capital flooded into the market. Under normal circumstances, such massive institutional support would easily propel the benchmark indices to fresh high-water marks.

    Instead, the Sensex retreated by three hundred and seventy-five points because direct retail participants took a defensive stance on the trading floor. Sensing high valuations and fearing the inflationary drag of an expanding trade gap, retail traders chose to take money off the table. The widening trade deficit serves as a persistent reminder of global volatility, oil-price exposure, and the immediate pressures facing the Indian Rupee. As retail investors navigate these mixed signals, their cautious retreat demonstrates a growing sophistication—a refusal to blindly follow institutional flows when macro headwinds mount. NI

  • Diaspora Inflows and Policy Reforms: Reading India’s Economic Pulse

    India’s macroeconomic landscape present a study in contrast, where easing real-economy momentum collides with proactive legislative intervention and structural financial stability. Macroeconomic indicators for July pointed to a pronounced cooling across the productive sectors of the economy. Manufacturing sector activity growth fell to a nearly five-year low, with the HSBC India Manufacturing Purchasing Managers’ Index slipping to 53.5. Softening domestic order growth, particularly within consumer goods, dragged overall expansion down to its weakest pace since August 2021. This momentum loss spilled into factor inputs: purchasing of raw materials dropped to a 31-month low, while job creation slowed to its weakest pace across a 29-month streak of hiring expansion. A parallel trend emerged in the service sector, where output growth sank to a 53-month low of 53.3, pulled down by softer order flows in most major categories except finance and insurance. Against the backdrop of softening real-sector activity, legislative reform moved aggressively to unlock structural bottlenecks within small enterprise supply chains. Parliament passed the Micro, Small and Medium Enterprises Development (Amendment) Bill, 2026. Designed to address chronic liquidity constraints and systemic payment delays, the legislation introduces strict procedural deadlines for dispute resolution, capping mandatory mediation at 90 days. To curb frivolous challenges, buyers appealing an arbitral award must deposit at least 50% of the disputed sum if the case remains unresolved after six months. Furthermore, the law grants district collectors direct recovery powers by declaring mediated settlements and arbitral awards enforceable as arrears of land revenue. To enforce financial discipline at the institutional level, Central Public Sector Enterprises are now mandated to settle procurement invoices via the Trade Receivables Discounting System. Accompanied by the decriminalisation of minor compliance lapses and the creation of a voluntary national digital registration portal, these reforms aim to safeguard a sector that generates over 30% of national gross domestic product and nearly half of total exports. While industrial and service growth moderated, the Reserve Bank of India expressed confidence after mobilizing nearly $41 billion in non-resident Indian deposits and foreign borrowings. This capital surge was driven by targeted central bank measures, including concessional foreign exchange swaps and deregulated interest rate caps on Foreign Currency Non-Resident accounts, offering tax-free dollar yields between 5.5% and 7.1%. To maintain durable long-term foreign exchange buffers and cushion against global volatility, the central bank confirmed that the special deposit window will remain operational through September 2026. Leveraging diaspora deposits offers a strategic trade-off compared to traditional multilateral loans from institutions like the International Monetary Fund or World Bank. While NRI deposits command higher interest costs and shorter tenures, they provide the country with complete policy sovereignty. Unlike IMF rescue packages, which enforce strict structural adjustments, austerity measures, and policy oversight, diaspora capital carries no political conditions or external mandates, allowing the central bank to manage balance-of-payments buffers autonomously. Financial markets reflected this broader structural resilience. Regulatory proposals by the central bank to standardise floating-rate interest frameworks across non-banking financial companies briefly rattled sector stocks due to fears of narrowing net interest margins. However, broader indices like the Sensex and the Indian Rupee remained remarkably stable. Institutional flows highlighted a distinct split in market participation: Foreign Institutional Investors recorded net purchases of ₹2,887.70 crore, while Domestic Institutional Investors injected a massive ₹7,767.50 crore into the market. This surge in domestic institutional buying highlights an ongoing structural transition among domestic retail investors. NI

  • The Missing Middle: A Tale of Two Indias in the Housing Market

    The skyline of urban India has never looked more ambitious, with glass-fronted towers and luxury estates redefining the horizons of cities like Mumbai, Gurgaon and Hyderabad. These structures are the physical manifestation of a staggering surge in private wealth that has reshaped the nation’s economic identity. According to recent data shared in the Lok Sabha, the number of individuals reporting an annual income of ₹100 crore or more—the elite “100-Crore Club”—has quadrupled in just five years, reaching a record 576 in the 2025-26 assessment year. This explosive growth in the INR billionaire class, alongside a sixty-three percent increase in ultra-high-net-worth individuals, has propelled luxury housing to unprecedented heights. For the first time, homes priced above one crore rupees account for more than half of the total residential sales value in the country. To a casual observer, the Indian property market appears to be in a golden age, fueled by a seemingly bottomless well of domestic and global capital.

    However, beneath this glittering surface lies a profound paradox. While the sales value of luxury properties is breaking records, the actual volume of inventory being absorbed has begun to stumble. Across the top seven metropolitan areas, the unsold stock of luxury housing surged by twenty-four percent annually by early 2025, with over one lakh units remaining vacant. In once-booming markets like Hyderabad and Mumbai, aggressive launches have outpaced the market’s depth. The “stumbling” inventory suggests that the initial post-pandemic buying frenzy has given way to selective maturity. Even the ultra-wealthy are becoming value-conscious, showing resistance to the double-digit annual price hikes of recent years. Many projects labeled as “luxury” are increasingly viewed as standardized products that fail to offer genuine exclusivity or “trophy asset” status that the new billionaire class demands.

    This saturation at the top is only one half of the story. The other half is a starkly different reality facing India’s lower and middle classes. While headline GDP growth in INR remains robust, the “ground-level” economy is struggling with a severe financial squeeze. Real wages, adjusted for inflation, have remained virtually stagnant for nearly a decade, with rural and informal sector workers seeing almost no increase in their purchasing power. At the same time, household debt has climbed to record levels, now estimated at over forty percent of GDP. This pincer movement of stagnant incomes and rising debt has effectively killed the affordable housing segment. The share of affordable homes in total sales has plummeted from thirty-eight percent in 2019 to a mere eighteen percent in 2024. Developers, squeezed by thirty to forty percent increases in construction costs, have largely abandoned the segment in favor of high-margin luxury projects. The result is a “missing middle” in the housing market, where those who drive the nation’s services and industry find themselves priced out of homeownership and trapped in a cycle of house rents.

    Adding a new layer of complexity to this fractured landscape is a significant shift in the sentiment of the global Indian diaspora. For decades, Non-Resident Indians (NRIs) were the bedrock of the luxury market, viewing ancestral soil as a safe and high-yield investment. However, the recent Remittor Annual NRI Wealth Report 2026 reveals a startling trend: 72% of NRI property owners are now planning to exit their Indian investments, 46% looking to sell immediately and 26% planning an exit within six months). This mass exit is driven by lower yields due to depreciating Rupee and a strategic shift toward global markets like Dubai, Indiana and Manchester where rental yields and tax structures are perceived as more favorable. The departure of the NRI buyer, who often held multiple properties as investment vehicles, further threatens the absorption of the massive unsold luxury inventory.

    The Indian real estate market thus stands at a critical crossroads, characterized by a “K-shaped” recovery that has detached the fortunes of the elite from the financial reality of the masses. The wealth engine that produced 576 billionaires is a powerful force, but it cannot sustain a healthy housing ecosystem in isolation. The stumbling luxury inventory and the vanishing affordable pipeline are symptoms of a market that has over-leveraged on the top tier while neglecting the foundational demand of the middle class. As the global Indian begins to cash out and the domestic middle class remains financially strained, the need for a structural recalibration has never been more urgent. A sustainable future for Indian real estate will require more than just record-breaking billionaires; it will require a market that builds for the many, ensuring that the dream of a home remains accessible to the families who are the true engine of India’s growth. US

  • From Japanese Pedometers to Global Guidelines: The Everyday Power of Walking

    Walking stands as one of the most accessible and effective forms of exercise available to nearly everyone. It requires no special equipment beyond a comfortable pair of shoes, costs almost nothing, and can be done almost anywhere. Health authorities consistently praise its ability to support weight management, strengthen the heart, improve mood and sleep, lower the risk of chronic diseases such as type 2 diabetes and certain cancers, and even extend life expectancy. While it may not build maximum muscle power or deliver the highest calorie burn in the shortest time, its low impact on joints and high sustainability make it ideal for long-term health. For many people, the best exercise is simply the one they will continue doing, and walking often wins that contest.

    The familiar target of ten thousand steps a day has deep roots in Japan, yet those roots are more commercial than medical. In the mid-1960s, around the time of the Tokyo Olympics, a Japanese company launched a pedometer called the Manpo-kei, which translates as “ten-thousand-step meter.” A doctor had voiced concern about declining daily activity as cars and modern conveniences spread, and the company responded with a device and a memorable slogan. The number itself was chosen largely because it was round, catchy, and the Japanese character for ten thousand vaguely resembles a walking figure. Later research added some scientific support by linking higher step counts to extra calorie expenditure, but the original figure was marketing first and evidence second. Modern studies show meaningful health benefits often begin at far lower daily totals, sometimes around four to seven thousand steps, with further gains continuing as volume and pace increase.

    The World Health Organization takes a different approach. Instead of prescribing a fixed number of steps, it recommends that adults accumulate at least one hundred fifty to three hundred minutes of moderate-intensity aerobic activity each week, or seventy-five to one hundred fifty minutes of vigorous activity, or an equivalent mix. Muscle-strengthening work on two or more days is also advised. Brisk walking counts fully toward the moderate-intensity goal. The organization stresses that any movement is better than none and that more activity generally brings greater benefits, while also urging people to reduce long periods of sitting. Walking for transport, recreation, or daily errands all contribute.

    Knowing whether an activity qualifies as moderate intensity is straightforward. The simplest method is the talk test: if you can speak in full sentences but cannot sing, you are working at a moderate level. Light effort allows easy conversation or even singing; vigorous effort leaves you able to manage only a few words between breaths. Another guide is the rate of perceived exertion on a zero-to-ten scale, where moderate effort feels like a five or six. Heart rate offers a more precise option. An estimate of maximum heart rate can be calculated by subtracting age from two hundred twenty. Moderate intensity typically falls between fifty and seventy percent of that maximum, while vigorous intensity reaches seventy to eighty-five percent. Absolute measures using metabolic equivalents place moderate activity between three and nearly six METs, the range that includes brisk walking at three to four miles per hour.

    Heart rate zones refine this picture further by dividing effort into five bands based on percentages of maximum heart rate. Zone one, at fifty to sixty percent, is very light and suited to warm-ups or recovery. Zone two, sixty to seventy percent, builds aerobic endurance and encourages the body to use fat for fuel while still allowing comfortable conversation. Zone three, seventy to eighty percent, feels moderately hard and strengthens cardiovascular capacity. Zones four and five push into hard and maximal efforts that improve speed, lactate threshold, and peak oxygen use, though they demand more recovery. Many people seeking general health spend most of their time in the lower to middle zones, consistent with the weekly minute targets from the World Health Organization. Fitness trackers can display these zones in real time, yet the talk test remains a reliable, equipment-free check that keeps effort honest.

    Walking delivers substantial benefits at almost no cost. The popular ten-thousand-step goal, while useful as motivation, is not a strict scientific threshold and was never an ancient Kampo prescription. Official guidance focuses on minutes of moderate or vigorous movement rather than steps alone. Intensity can be judged simply by the ability to talk, by how hard the effort feels, or by heart-rate percentages organized into useful training zones. Anyone can begin with a daily walk at a pace that raises the breathing just enough to make singing impossible, then gradually expand duration or introduce varied efforts. The result is a sustainable path toward better health that fits into ordinary life

  • Caste, Secularism and the New Majority in Nepal

    The southern border plains of Nepal, a region historically known as the Terai-Madhesh, are once again engulfed in a volatile mix of communal violence and deep-seated political identity struggles. The recent eruption of unrest in late July 2026, sparked by seemingly minor local disputes over loud music and the replacement of a community flag on an electricity pole, quickly transformed into violent clashes. As mobs engaged in looting and arson, the secular Nepalese state responded with firm security measures, deploying the Nepali Army and imposing strict curfews. When security forces used live ammunition to quell the escalating riots, three individuals—all associated with the Hindutva-led mobilisation—were killed in Sunsari and Siraha districts. This heavy-handed state intervention has triggered a direct stand-off between hardline Hindutva demonstrators and the state security apparatus. Beneath the immediate smoke of burning businesses lies a deep-rooted dispute over demographic representation, political legitimacy, and historical engineering. For decades, official census data has classified nearly 81 percent of Nepal’s population as Hindu. However, secular analysts, indigenous leaders, and Dalit activists argue that this sweeping monolithic statistic is a relic of previous autocratic regimes that enforced cultural assimilation. Historically, under the absolute monarchy and strict legal codes like the 1854 Muluki Ain, diverse Buddhist, animist, and indigenous communities—the Adivasi Janajati or mool nivasis—were systematically integrated into the lower rungs of the Hindu caste hierarchy, often designated as Shudra or marginalized castes. This historical state engineering sought to construct an artificial, unified religious canopy that inherently privileged the traditional ruling elite. This traditional elite is composed primarily of Hill Brahmins and Chhetris, who together constitute roughly 28 percent of Nepal’s total population. Despite their minority demographic status, this elite group has historically maintained an absolute monopoly over the country’s political parties, civil bureaucracy, judiciary, and military. Critics argue that the majoritarian slogans currently being chanted by hardline Hindutva groups are strategically fake. By framing localized disputes as existential crises for the majority religion, these organizations—frequently operating under local front groups like the Hindu Samrat Sena—attempt to project an “us versus them” narrative. The primary political goal of this strategy is to foster an aggressive religious identity that supersedes caste and ethnic divisions. By doing so, they hope to pressure the indigenous, Dalit, and Shudra majority, who make up the remaining 72 percent of the country, to fall back under a monolithic Hindu identity, thereby preserving the traditional caste-based social and political hierarchy. However, the contemporary political landscape of Nepal makes this assimilation strategy increasingly difficult to sustain. The historic, youth-led “Gen Z” uprising in September 2025 radically disrupted the status quo, forcing the resignation of the old political guard and dissolving the traditional power structure. In the subsequent political alignment, a new generation of leaders has emerged, bringing the historically marginalized majority into unprecedented positions of leverage. The current Prime Minister, Balendra “Balen” Shah, hailing from the Madhesi community, embodies this shift away from the Hill Brahmin monopoly, leading a fragile and pluralistic federal coalition of regional parties, indigenous Janajati fronts, and secular youth factions. This current communal explosion is therefore viewed by social scientists as a direct conservative backlash against the political awakening of the Shudra and indigenous majority. As these historically marginalized groups increasingly assert their secular, identity-based rights under the country’s federal structure, hardline factions are escalating their tactics to manufacture a “Hindu-in-danger” panic. The open border with neighboring India has allowed these groups to draw ideological inspiration, rhetoric, and social media polarization strategies directly from broader subcontinental majoritarian movements. While proponents of a Hindu state argue they are merely preserving a historical, civilizational identity against foreign secular influences, indigenous and Dalit organizations view the movement as an existential threat to their hard-won autonomy. The ongoing state-enforced lockdowns along the southern trade corridors reflect a nation caught in a profound transition: a secular government attempting to maintain neutral law and order while a newly empowered, diverse majority resists the structural re-imposition of a historical, minority-led religious hierarchy.